
Emergency Fund for Irregular Income: A Practical Global Guide
If your pay goes up and down, it can be hard to save the same sum each month. You can still set cash aside. Start with bills you must pay. Save part of each payment when it comes in.
Start with the risk, not a magic number
An emergency fund is cash you can use when life goes wrong. It is not for a sale, a trip, or a new phone. It helps pay urgent bills or fills a gap when work slows. If you earn steady pay, you may save the same sum each month. If you work shifts, run a shop, or take short jobs, that may not work. Your bills can stay the same even when your pay falls.
Start with bills you must pay to keep life on track. Write down rent, food, power, travel to work, medicine, and debt dues. Leave out things you can pause, like films, meals out, or new clothes. The first goal is simple: pay the basics if work stops or a client pays late.
The best emergency fund size is not the same for each person. It depends on your fixed bills, how much your income moves, who relies on your pay, and how fast you could earn again. A person who has one employer and a second source of household income may need less cash than a sole earner whose work comes in bursts.
Find your monthly floor
Look at the last three months of bank and card records. Use actual bills, not rough guesses. Put each essential cost in its own row and note whether it is due each week, month, or year. Divide yearly costs by twelve, but do not count every annual expense as an emergency. Regular car tax or school fees, for example, belong in a planned savings fund.
Say your core bills are 900 units of your local currency each month. Your first milestone could be 900: enough to buy one month of breathing room. Three months would be 2,700. Six months would be 5,400. The amounts are examples, not market rates or a fixed rule for every country. If your core costs change, your target must change as well.
Use the same currency as your bills. If you are paid in one currency and spend in another, allow for exchange-rate swings and transfer delays. Count an asset as emergency cash only if you can access it soon, without a large loss or penalty.
Use a two-layer target
A useful approach has a starter layer and a full layer. The starter layer covers one urgent bill or one month of essential spending. It stops a small problem from becoming costly debt. The full layer holds several months of core costs. The right span may be three to six months for some homes, but more may be sensible if work is scarce or pay is highly uneven.
Do not wait to pick a perfect six-month sum before saving. Put aside a small amount on the next good payday. Build one month first. Then review the risk. A worker with a long notice period, strong benefits, and support at home may make a different choice from a solo worker who earns most of the year’s pay in a short season.
A simple risk check
Ask how long it took to find paid work the last time demand fell. Ask how much notice clients give before a job ends. Ask if someone in your home could cover food and rent for a short time. The more fragile the answers, the more useful a larger cash buffer may be. This is a planning test, not a score used by a bank or insurer.
Save from each payment instead of each month
Monthly automatic transfers work well for fixed salaries. They may fail for income that arrives on odd dates. A more useful habit is to move a set share whenever money lands in your account. Start with a share you can keep up, even in a slow month. You can raise it in strong months.
For example, a designer receives 1,800 units for a project. After setting aside the amount needed for tax and current bills, they move 90 units to emergency savings. A week later, a small job pays 300, and they move another 15. The 5% share is only an illustration. The right rate depends on debts, tax rules, family needs, and cash flow.
Do not save tax money in the same pot as an emergency fund. Tax is a known future bill, even if the date or final amount varies. Keep it separate. The same is true for rent due next week. An emergency balance that includes money already owed can give a false sense of safety.
Keep the fund safe and easy to reach
The main job of emergency savings is access, not the highest return. Look for a regulated deposit or savings option in your country with clear withdrawal rules. Check whether deposit protection applies, what the coverage limit is, and whether that protection is per person, account, or institution. The rules vary across borders.
A separate savings account may stop you from spending the balance by habit. Yet a locked account can be a poor match if it takes weeks to release cash. You might keep a small amount for same-day needs and the rest in an account that transfers within a few working days. Test a small transfer before you trust the setup.
Money market funds and bond funds are not the same as insured bank deposits. Their value and access can change. Short-term investing can be useful for other goals, but cash that must pay tomorrow’s rent should not rely on a market sale at a good price.
Know which events count as emergencies
Your fund should have a clear rule. A sudden medical bill, critical home repair, urgent trip for family care, or job loss may qualify. A yearly insurance bill or planned holiday does not. If you use the fund for a predictable cost, the problem may be your budget rather than the size of the fund.
Imagine your laptop fails just before a client deadline. If your work depends on the machine and a low-cost repair will get you paid again, that repair may be a true emergency. A premium model upgrade is a separate choice. Spend what solves the problem safely, keep the receipt, and note why you used the money.
Make a withdrawal rule
Before you withdraw, ask: Is this cost urgent? Is it needed to protect health, housing, income, or safety? Is there a cheaper safe fix? Can I pay from an existing budget line? These four checks reduce regret without making it hard to use the money when you truly need it.
Plan for late pay and weak seasons
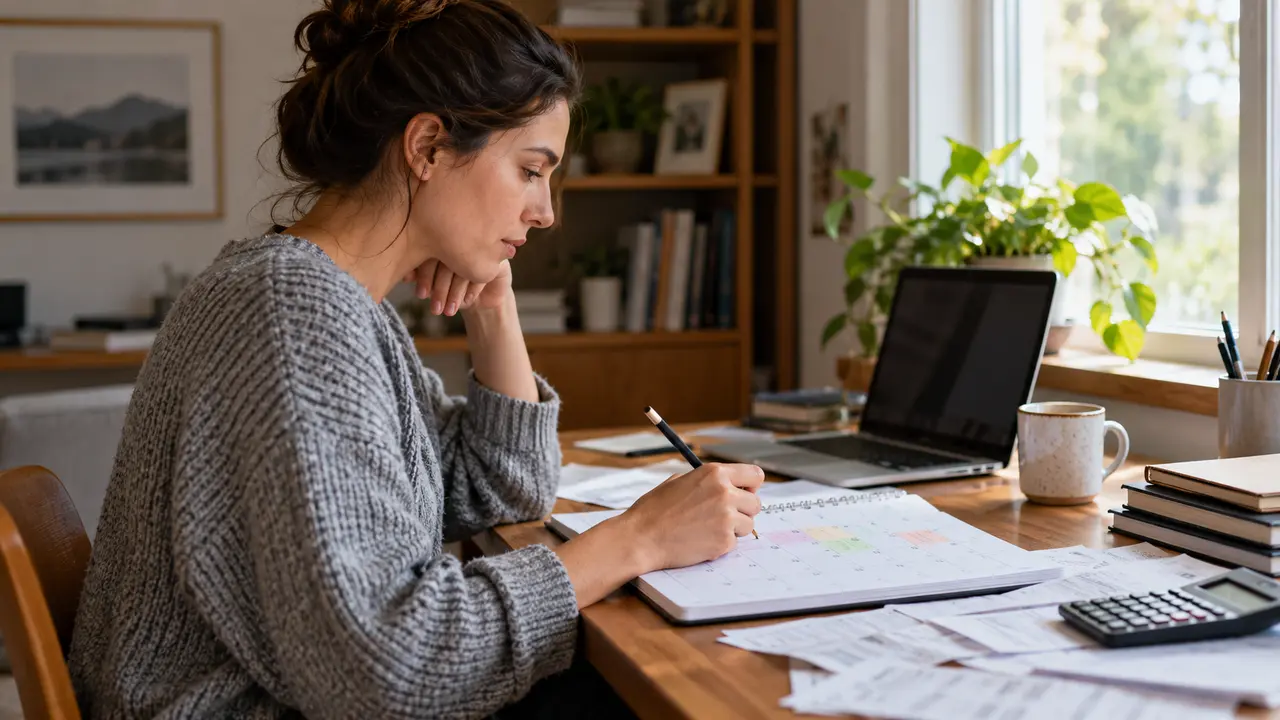
A late invoice does not always mean you have lost the money. But it can still cause real harm if a payment is due first. Make a simple cash calendar. Mark when rent, utilities, loan payments, and other core bills fall due. Next to them, mark pay that is confirmed and pay that is only expected. Treat expected pay with care.
If a client is late, contact them at once and ask for a firm date. Send a clear invoice record. If a bill will also be late, contact the provider before the due date to ask about a safe payment plan. Do not assume a grace period applies in every country.
A seasonal worker can use a strong season to fill the fund before the slow season begins. Set a target for the number of low-income weeks you face. If your income goes up sharply for one month, resist raising your fixed bills at the same pace. That leaves room to save.
Rebuild after a withdrawal
Using an emergency fund for a real emergency is not a failure. It is the reason the fund exists. Once the event is over, check how much remains and set a short rebuild plan. If income has fallen, keep the plan small enough that food and housing are safe. If income has recovered, direct a share of each new payment back to the fund.
Suppose a repair takes 600 units from a 2,400-unit balance. You now have 1,800 left. You could aim to restore 600 over six pay cycles by saving 100 each time. If those pay cycles are not equal, use a share of each payment instead. Do not use expensive debt just to make the savings balance look whole.
Review the fund twice a year and after any big change, such as a move, child, new contract, or higher essential bill. Inflation can raise your monthly floor even when your habits stay the same. Your target should follow actual costs, not last year’s round number.
Avoid three costly mistakes
The first mistake is counting a credit card limit as savings. Credit can be cut, carries fees or interest, and creates a bill at the worst time. The second is putting emergency money into a risky asset because its recent return looks strong. A sharp fall may come just when you need the cash. The third is setting a goal so high that you stop before you start.
These issues matter in a world where financial access is rising but safety is still uneven. The World Bank Global Findex 2025 is based on surveys of about 148,000 adults across 141 economies. Its broad view of saving, payment habits, and financial risk is a reminder that an account alone does not solve every cash crisis. The survey is global, but it does not prescribe one emergency-fund amount for all households.
A strong plan is plain: know your essential bills, save after each payment, choose an accessible place, use the money only for a true shock, and rebuild with care. Those steps are simple enough to repeat even when your income is not.
A 30-day setup plan
During the first week, list core costs and add up one month of essential bills. In the second week, check the rules and access speed of a safe local savings option. In the third, choose a fair share of each incoming payment and move the first amount. In the fourth, write your withdrawal rule and test how you would reach the money.
If you cannot save this month, do not hide that fact with a fake target. Review one bill you can cut, see whether a provider offers a fair plan, and find the next small chance to start. For many people, the hardest step is making the system fit real pay dates. Once the system fits, each payment can make the buffer a little stronger.
This article is general education, not personal financial advice. Savings products, bank safeguards, taxes, and debt rights differ by country. Check the rules of your own regulator and institution before choosing an account.

2 Comments