Before You Co-Sign a Loan: Check the Payment Risk, Credit Impact and Exit Plan
A family member or friend asks you to co-sign a loan. They promise to pay every month, and you want to help. Yet a signature can turn their debt into your legal responsibility. Before you agree, slow down and test what would happen if they could not pay for six months.
This guide explains practical questions to ask before co-signing a personal, car or education loan. It is for a global audience. Loan contracts and credit reporting rules differ by country, so confirm the terms with your lender and local consumer authority. Do not treat a friendly promise as a substitute for the contract.
Know Exactly What You Are Signing
A co-signer usually supports another borrower’s application by agreeing to repay if the borrower fails to do so. The Consumer Financial Protection Bureau says a US co-signer takes on shared responsibility for a car loan and may be asked to pay when the primary borrower does not. The same broad risk exists in many markets, but the exact duties come from your local contract.
Read whether you are a co-signer, joint borrower, guarantor or another type of party. These labels may have different legal effects. Ask the lender in writing whether it can seek payment directly from you, what happens after a missed payment, and whether your liability includes interest, fees and collection costs.
Do not assume you own the asset
On some loans, helping repay does not mean you own the car, home or item bought with the money. You could be responsible for payments without having a right to use or sell the asset. Check legal ownership separately from debt responsibility.
Run the Payment Test on Your Own Budget
Write the loan’s full monthly payment into your budget as if you must pay it yourself. Could you still cover rent, food, insurance and your own debt? If the answer is no, the risk is larger than your current finances can comfortably hold.
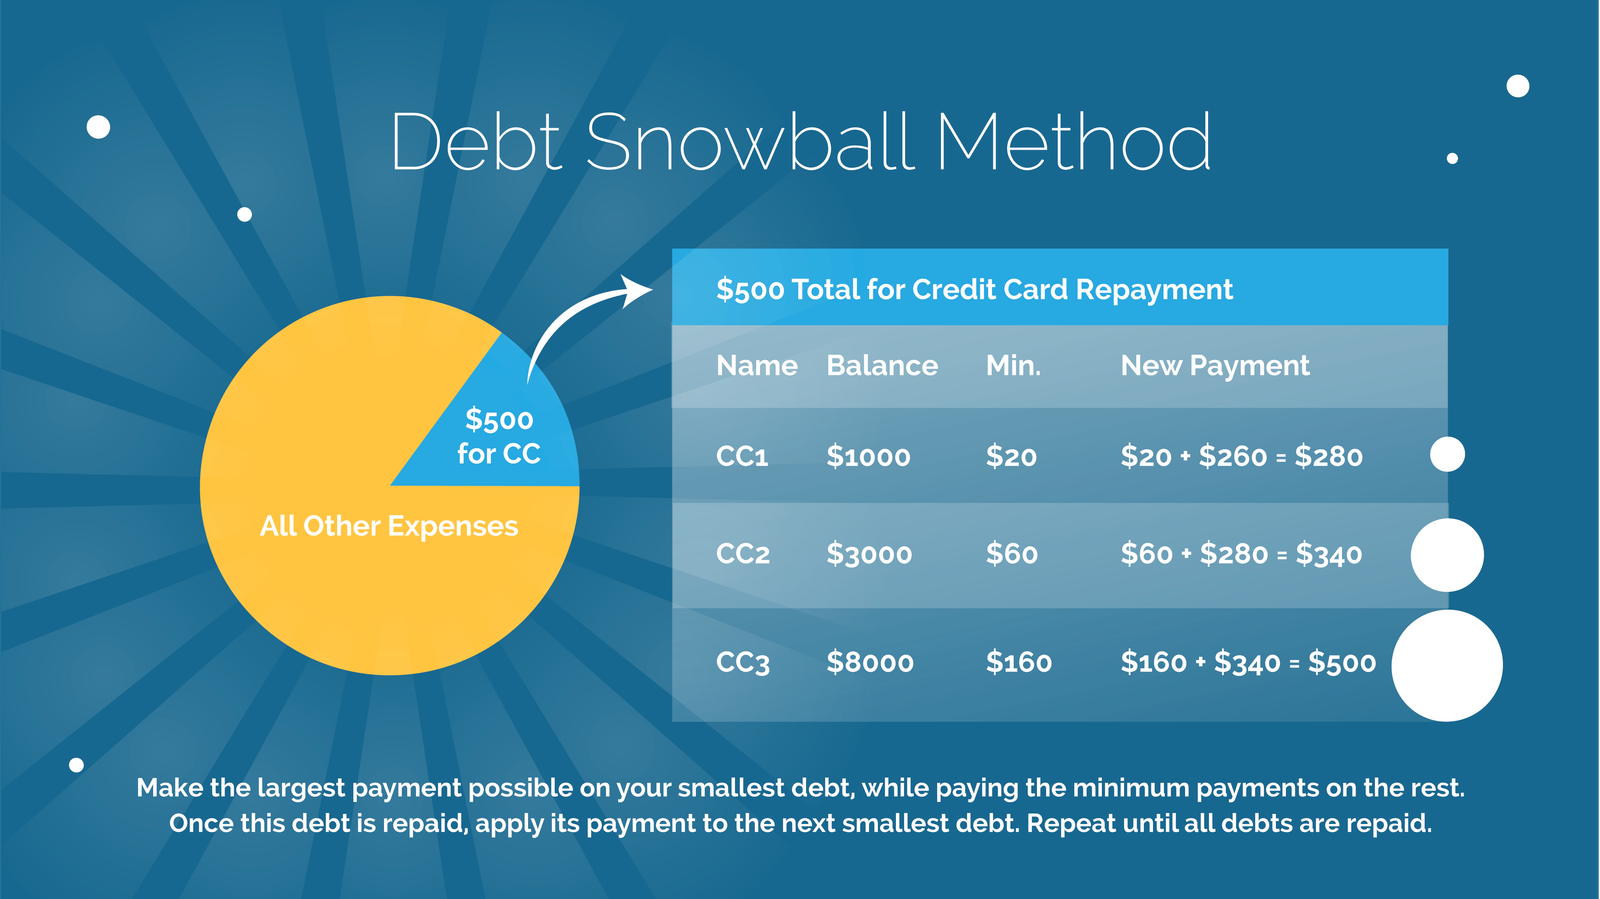
Imagine the loan payment is 280 units per month. If the borrower misses six payments, the amount due could be 1,680 before late charges and interest effects. That is a simple example, not a prediction. The real liability may be much more, especially if the lender accelerates the balance or adds costs under the contract.
Look beyond this month’s cash
Ask whether your own income is secure. Think about planned expenses, a move or a change of job. A loan that fits today may be difficult next year. If you are saving for your own borrowing, consider how the co-signed debt could affect your application.
The CFPB’s student loan co-signer guidance notes that co-signers can face serious consequences when a loan defaults. The exact credit effect depends on the reporting system where you live, but a lender may still count the commitment when assessing your ability to borrow.
Talk About the Borrower’s Backup Plan
Ask the borrower to show how they will repay, including a realistic income estimate, existing debt and regular living costs. You are not demanding control of their money. You are checking whether both of you understand the same risk.
A good discussion covers what happens after job loss, illness, a late wage payment or an unexpected repair. The borrower might have savings or another source of income. If there is no plan, the loan may depend on luck rather than a sound budget.
Keep the talk practical
Instead of saying ‘You will never miss a payment, right?’, ask ‘If a payment is due and your salary is late, who will pay that month and how will we know?’ A clear answer is more useful than reassurance. If the conversation becomes hostile, that may be a sign that the arrangement is not ready.
Understand the Credit Impact
Depending on local credit systems, the loan may appear on your credit record or be considered by a future lender. Missed payments can affect the borrower and co-signer. The CFPB highlights this risk for co-signed student loans in the US.
Ask whether the lender reports the loan to credit bureaus, which parties are listed, and how payment history is handled. If your country has no similar reporting system, the debt can still be a legal financial obligation. Do not assume a clean credit report removes it.
Plan for a future loan of your own
Suppose you hope to apply for a mortgage or business loan next year. A lender may consider the co-signed payment when reviewing your commitments. You could have to provide records showing who actually pays, and that may not remove liability. Ask your proposed lender how it treats the loan before signing.
Check Every Cost and Trigger
Read the interest rate, whether it is fixed or variable, the term, total repayment amount, late fee rules, security and insurance requirements. Check whether a missed payment changes the rate or allows early repayment to be demanded. A small monthly figure can hide a long and costly obligation.
Ask how payments are applied when the borrower is late. Do they go first to fees, interest or principal? Can the lender use an automatic payment method linked to your account? Do not give account permissions you do not understand.
Notice joint promises
Some contracts may make each signer responsible for all the debt, not half. A private plan to split the balance may not change what the lender can collect. If the contract is unclear, get qualified local advice before signing.
Find Out Whether You Can Be Released
Some loans include a co-signer release option after a set number of on-time payments and a fresh credit review. Others have no release process. The CFPB advises checking for release options on private student loans. The criteria and availability depend on the product.
Ask for written answers: When can release be requested? Who must apply? What documents are needed? Does the lender have to approve? Can refinancing remove your name? A verbal hope that the borrower will refinance soon is not an exit plan.
A release is not automatic
Even if the borrower pays well, the lender may require their income and credit to qualify on their own. Mark the earliest review date on a calendar, then check the policy’s current rules. Do not stop monitoring the loan until you have written confirmation that you are no longer responsible.
Set Up Payment Visibility
If you do co-sign, ask whether the lender can send you account statements or missed-payment alerts. Do not wait for collection calls to learn that there is a problem. Agree with the borrower on a monthly check-in that respects privacy but gives you enough information to protect yourself.
Keep your own copy of the signed contract, payment schedule and lender support details. Record every payment you make on the borrower’s behalf. If repayment between you is agreed, document it and get local advice on whether the arrangement is enforceable.
Do not rely on screenshots alone
A screenshot of a payment promise may not show whether the lender received and applied the money. Whenever possible, use an official account statement or confirmation. If a payment is missed, contact the lender promptly to understand available options and deadlines.
Consider Safer Ways to Help
You may be able to help without taking on the entire loan. You could contribute a one-time amount you can afford to give, help the borrower compare cheaper options, review their budget, or delay the purchase until savings are stronger. These choices have different personal and tax effects, so keep the agreement clear.
If you lend money directly, consider that it may not be repaid and could strain the relationship. Avoid using funds needed for your own essentials. The most helpful choice may be a firm but kind no.
A realistic conversation
You might say, ‘I care about helping, but I cannot afford the full payment if something goes wrong. I can help compare loans and plan a deposit instead.’ This keeps the discussion focused on risk rather than trust. A responsible decision can protect both people.
A Co-Signing Checklist
- Confirm your exact legal role and full liability
- Calculate total debt, interest and possible fees
- Test the full payment against your own budget
- Ask how missed payments and credit reporting work
- Check the borrower’s backup plan
- Get co-signer release rules in writing
- Set up statements, alerts and document storage
Pause if you cannot obtain the contract in advance, if someone is pushing you to sign quickly, or if the numbers do not add up. A co-signed loan can last for years. Taking a few extra days to read it is reasonable.
Questions People Ask
Can I remove my name later?
Only if the lender and local rules allow it, such as through approved release or refinancing. Do not assume paying on time guarantees removal.
Do I become the owner of what was bought?
Not necessarily. Debt liability and ownership are separate questions. Check title or registration documents.
What if the borrower misses one payment?
Contact the lender and review the contract promptly. Your obligation and credit effects depend on the terms and local rules. Waiting can make the problem more costly.
Co-sign only when you understand the whole debt, can handle the worst realistic payment gap, and have a clear monitoring and exit plan. Helping someone should not put your own basic needs at risk.