How Families Can Share Caregiving Costs Fairly: A Practical Money Plan
When a parent or relative needs help, one person may start paying for transport, meals, medicine or home supplies. Another may give time but little cash. A third lives far away and wants to contribute. Without a clear plan, even a caring family can end up with confusion and resentment.
This guide is about organizing shared costs, not giving medical advice or deciding who owes what under law. Families around the world have different customs, resources and support systems. The goal is to make expenses visible, respect unpaid care work and agree on a fair method before money becomes an argument.
Separate the Person’s Money From Family Contributions
Start with what the person receiving care can and wants to pay from their own funds, benefits or insurance. Do this with their informed consent and within local legal rules. Their money is not simply a family pool. If someone handles it on their behalf, ask what legal authority and record-keeping duties apply.
The Consumer Financial Protection Bureau provides guidance on managing someone else’s money and keeping the person’s interests first. Its tools are US-based, but the principle of separating funds and keeping records is useful in many places.
Make a basic monthly picture
List recurring needs such as transport to appointments, food delivery, home help, mobility supplies and utility changes. Then add less frequent costs, such as equipment replacement or a home adaptation. Note which expenses are already covered by insurance, public support or the person’s own income.
Do not mix medical decisions with financial pressure. If care needs are uncertain, ask a qualified professional or care coordinator about the practical options. Then budget for the option the person chooses.
Count Time as Well as Cash
A family member who drives to appointments or spends evenings helping may not pay many receipts, but their time has value. Another person may cover more money because they live abroad. Both can contribute in different ways. A fair plan should recognize that instead of ranking people by cash alone.
At the WHO’s 2026 Global Caregiver Forum, the organization highlighted the often unseen strain of unpaid care on health, work and finances. That is a reason to make care duties part of the discussion, not only the bills.
Create two simple records
Use one sheet for money paid and one for time or tasks given. The task sheet need not put a price on every hour. It can show who handles shopping, transport, calls, paperwork and respite. This makes invisible work easier to discuss and share.
Choose a Contribution Method That Fits
Equal shares sound simple, but household incomes may differ. One sibling may have a high income and another may be between jobs. A fixed equal payment could leave one person under strain. You can compare three methods: equal cash shares, shares based on ability to pay, or a mix of money and agreed care tasks.
For example, a monthly uncovered care budget of 600 units might be shared as 200 each by three adults. But if one adult can afford only 80, the others could voluntarily cover more while that person takes on agreed tasks. This is a sample, not a rule. Write the arrangement down and review it when circumstances change.
Avoid hidden obligations
Do not assume a person will pay because they are the oldest, closest or most successful. Ask what they can commit without harming essential needs. A contribution that people can keep making is better than a large promise that fails after two months.
If one person pays first, agree when others will reimburse them and how receipts will be shared. Do not force anyone to reveal private salary details. A simple contribution range may be enough for a fair conversation.
Make a Shared Expense Ledger
A notebook or shared spreadsheet can work. Record the date, item, amount, who paid, whether it was approved, and whether reimbursement is due. Keep receipts or photos in a private folder. Protect medical and financial details by limiting access to people who need them.
Use a monthly closeout
At the end of each month, total approved costs and contributions. Check for missing receipts or double entries. Then settle reimbursements once rather than sending many small requests during the week. This reduces pressure on the person doing daily care.
A sample entry might read: transport to clinic, 30 units, paid by A, approved by family, reimbursement split under agreement. Avoid vague labels such as ‘other costs’ for large amounts. Clear notes build trust.
Plan for Irregular and Emergency Costs
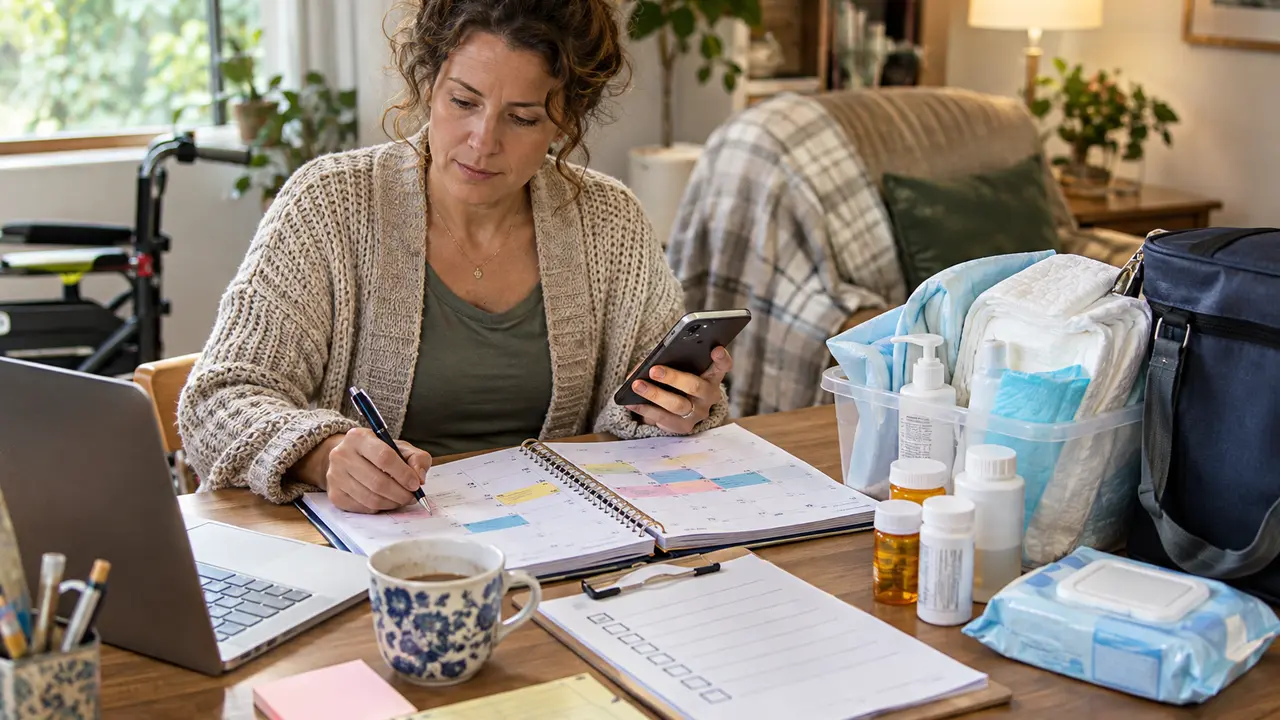
A monthly care budget can miss sudden equipment, home repair or extra travel needs. Keep a small reserve if the family can afford it. Agree on a threshold: for example, routine costs under a set amount can be handled by the main caregiver, while larger optional purchases need a discussion.
Safety needs cannot always wait for a vote. Make an emergency contact plan and a rule for urgent spending that follows the care recipient’s wishes. Agree how to report what happened afterward.
Use realistic estimates
Review the last three months if records exist. If there is no history, start with one month and revise quickly. Do not pretend to know the exact cost of future illness or support. Budget ranges are more honest than a perfect number.
Protect the Main Caregiver From Burnout
Money can help pay for transport, meal support or respite, but a caregiver may also need time off. Ask who can cover a regular break, even if it is only a short shift each week. If family members live far away, they may help book services, handle calls or take a planned visit.
The WHO caregiver-support materials address the burden and financial cost of care. Families should treat the caregiver’s well-being as part of the plan, not a bonus after everyone else is covered.
A practical task swap
One adult may handle weekday care, another may take weekend shopping, and a third may manage bills and service bookings. Write down who does what and a backup person for each task. If no one can cover a duty, discuss paid support where available and affordable.
Keep Decisions Respectful and Clear
Hold short meetings with an agenda: current needs, money spent, tasks, changes and next review date. Give the person receiving care a voice whenever possible. Avoid discussing private health details in a large group or making decisions based only on the loudest relative.
A family member may disagree with a purchase. Ask what problem the purchase solves and whether a safer or less costly option exists. Do not treat every disagreement as bad faith. Evidence and clear limits make the discussion easier.
When trust is low
Use written approvals for larger costs and consider a neutral mediator or qualified professional if needed. Do not put another person’s money into a personal account without checking the legal and financial implications. Keep a separate record of all transfers.
Review the Plan When Care Changes
Care needs, income and family availability can shift. A budget that worked last season may no longer fit. Review costs after a hospital stay, job change, move or change in support services. If the care recipient’s wishes or capacity change, seek appropriate local guidance on decision-making authority.
- List the person’s available resources and permissions
- Record recurring and irregular care expenses
- Recognize unpaid tasks and time
- Agree on affordable contribution shares
- Keep receipts and reimbursements clear
- Set urgent-spending and approval rules
- Review support and caregiver breaks each month
Give the plan a clear owner for record keeping, but do not make that person the sole decision-maker by default. Good records help everyone participate fairly.
Common Questions
Should every sibling pay an equal amount?
Not necessarily. Equal cash shares may be simple, but a fair method can reflect ability to pay and unpaid care tasks. Agree openly and review it.
Can one family member use the care recipient’s bank account?
Only with the person’s consent and appropriate legal authority under local rules. Ask the bank or a qualified adviser rather than assuming family status gives access.
What if someone promises to contribute and stops?
Return to the written plan without blame. Check what they can now afford and whether tasks can be shared in another way. Update the budget so essential care does not depend on an uncertain promise.
A fair caregiving money plan is not just a split bill. It is a clear record of needs, resources, tasks and decisions that respects the person receiving care and the people helping them.