
Renters Insurance: Protect Belongings and Check Liability Gaps
The owner may insure the home, but that may not cover your things. Make a list of what you own. Learn what a renters plan may pay, check its limits, and plan ahead for claims.
Do not assume the landlord covers your things
Your landlord may have a plan for the house or flat. It may not pay if your clothes, laptop, bed, or chair is lost or stolen. You may need your own plan. It may help cover your things and some claims made by other people.
The National Association of Insurance Commissioners notes this gap for US renters. Plans and laws vary by place. Check your lease and the cover sold where you live.
Do not buy a plan just for its name. Read what it covers. Some plans name each risk. Others cover a wide range of sudden loss but leave some causes out. The words in the plan matter.
Make a simple home inventory
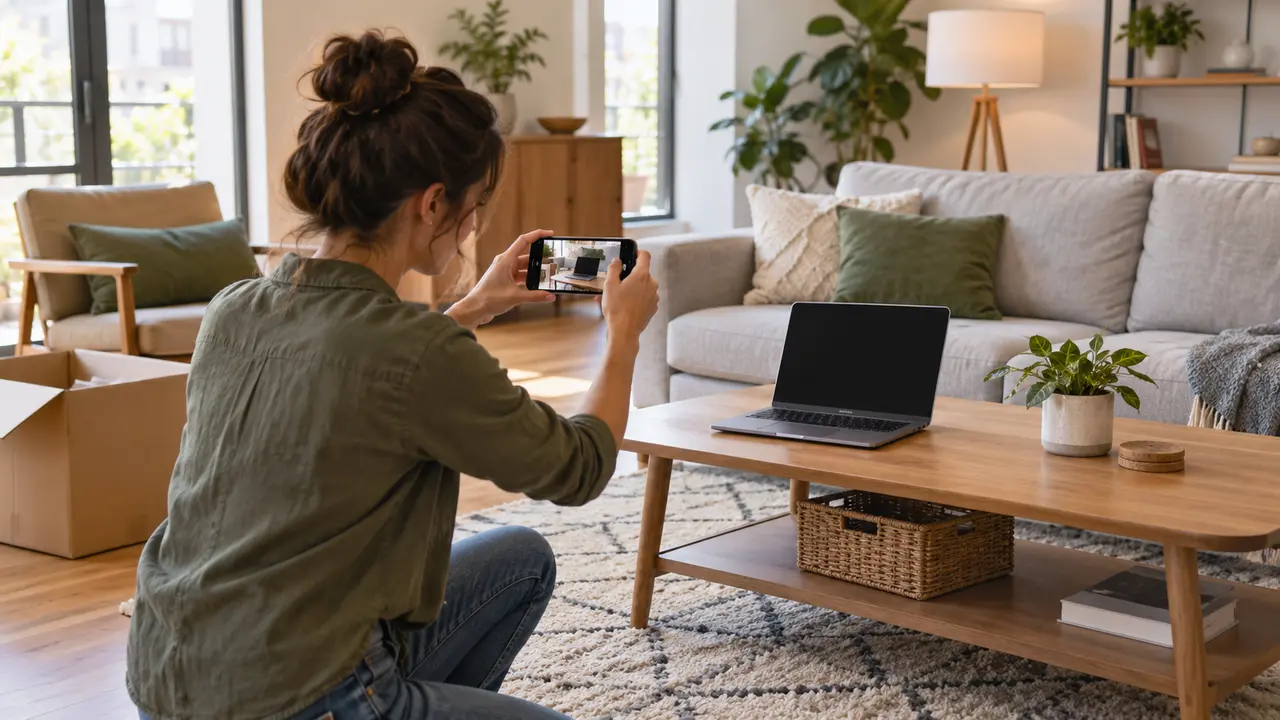
Go room by room and make a list. Add clothes, beds, chairs, phones, and work tools. For each costly item, note its age and what a new one may cost. Keep a bill or photo if you have one. A clear list can help if you need to make a claim.
Do not spend days counting every spoon. Start with things that would be hard to replace at once. Group low-cost items such as kitchen goods and clothing, then add the larger pieces. A rough full inventory can reveal a larger total than you expected.
Keep your list and photos in a safe place outside your home. A safe online file or a paper copy may work. Do not post photos of your things or bank details for all to see.
Choose a realistic contents limit
The contents limit is the most a plan may pay, based on its rules. It may not match what you paid for your things. Some plans pay for new items. Others cut the value for age and wear. Ask how the firm sets each claim and whether one item has a cap.
Suppose you have 12,000 units of belongings but only 5,000 of cover. A major covered loss could leave a large gap. Yet buying a huge limit you do not need may waste money. Use your inventory to set a fair amount.
Check special item limits
Rings, bikes, art, and work tools may have low caps. You may need more cover for them. Read the list of limits and ask the firm before you buy.
Know which losses are covered
A plan may pay for theft, fire, smoke, or some leaks. But it may not pay for slow damp, poor care, floods, or quakes. Some plans have strict rules for theft. Check the rules where you live.
Ask which events are likely where you live. An upper-floor flat may have a different water risk from a ground-floor home near a river. A city renter may worry about theft; another may need storm cover. Match the policy to real threats.
Ask for written answers to hard cases. If a neighbor’s pipe bursts, does your plan cover your belongings? If a river floods the room, is that covered? Do not trust a vague yes from an advert.
Understand the excess you pay
An excess is the sum you pay on a claim. Some places call it a deductible. A high sum may cut the price of the plan. But it can make a small claim of little use. Check if it applies each time.
For example, if a covered loss is 800 units and the excess is 300, the insurer may pay 500, subject to other terms. If the loss is below the excess, there may be no payment. This is simple math, not a promise of a claim outcome.
Keep enough cash to cover an excess without missing rent or food. Do not choose the highest excess only to get a cheap quote if you could not pay it after a loss.
Look at liability cover
Some plans help if you are held at fault when a guest gets hurt or you harm a person’s things. This is known as liability cover. The law and your plan set the limits. Do not assume all such claims will be paid.
For example, a visitor might slip in your home. Whether you have legal responsibility and whether the insurer pays are two different questions. Do not assume all accidents are your fault or all claims are covered. Ask about limits and exclusions.
The NAIC renter guide describes personal property and liability as two basic types of cover in many policies. Check if both are included in your exact plan.
Ask about a place to stay after damage
If a covered event makes the home unsafe, you may need a hotel or short-term rental. Some policies help with added living costs. Others do not. Ask when this cover starts, how long it lasts, and the total limit.
A policy may pay only costs above your normal spending. It might need proof that you cannot live in the home. Keep receipts and ask the insurer before booking a costly stay if it is safe to do so.
Do not assume a landlord must pay for every hotel bill. Rights vary by country and lease. Check local tenant rules and the policy separately.
Read the rules for shared homes
If you share a home, ask whose belongings are covered. A plan for one person may not protect a flatmate. Partners, children, and other household members may have different rules. Put the right names on the policy where required.
If you rent a furnished place, find out which items belong to the owner and which are yours. The landlord’s plan may cover their own sofa but not your laptop. If the lease makes you responsible for damage to furnished items, ask what cover applies.
Keep a move-in record and photos of the home’s condition where legal. That helps with deposit issues and can also support a claim after a covered event.
Check items used for work
A person who works from home may own a laptop, camera, or tools that help earn income. A standard renters’ policy may cap business gear or exclude some use. Ask about the item and its job before you rely on personal cover.
If clients visit your home, liability risks may change. The insurer may need to know. Be honest about work use. A policy set up for a normal home may not cover a business loss.
Separate business insurance may be needed for some work. Check local rules and seek licensed advice if the gear or business risk is large.
Make a claim file before you need one
Know the claim phone number, report deadline, and proof rules. Keep the policy, inventory, photos, and receipts in a safe place. If theft occurs, local rules may require a police report. If water or fire damages the home, take photos only when safe.
Protect people first. Do not enter a dangerous building to gather proof. Tell the insurer what happened and ask what to do next. Keep a note of calls, dates, and case numbers.
A short claim checklist
Record the event, date, damaged items, photos, any official report, urgent costs, and what the insurer says. Save decisions in writing. If you disagree, use the formal complaint process that applies locally.
Compare quotes with the same risks
Do not compare price alone. Use the same contents value, key events, liability amount, extra living cost limit, and excess where you can. A cheap plan that leaves out the main local risk may not help much.
Check the insurer’s legal name with your local regulator. Ask about renewal prices and cancellation rules. Read how claims are valued and whether your expensive items need a special list.
This article is general insurance education. Products, tenant rights, and claims rules vary by country. Use the inventory and questions to compare real terms sold in your area. The goal is cover that makes sense for the things you own and the risks you face.

One Comment