
Insurance Renewal Checklist: What to Review Before You Pay Again
Before you renew: Look past the new price. Check what the policy pays for and what it leaves out. Read the claim limit and the sum you must pay yourself. Tell the insurer what changed this year. Compare plans that give the same cover. Keep a copy of the final terms.
An insurance renewal notice can look like routine paperwork. You see the new price, check that you can pay it, and move on. Yet the cost is only one part of the decision. Your needs may have changed. A policy may have new limits, deductibles, or exclusions. The insurer may also use a new value for your home, car, or belongings. A short review before renewal can prevent a costly gap later.
This guide helps you review a personal insurance policy in plain language. It covers a method you can adapt to home, vehicle, travel, or other cover. The policy terms and consumer rights vary by location, so use your local documents as the final source of truth.
Start before the payment date
Put the renewal date on your calendar as soon as the notice arrives. Try to give yourself enough time to ask questions, compare cover, and arrange any switch without a gap. If a policy renews automatically, check the date by which you must cancel or change it. Do not assume turning off a card payment cancels the contract.
Gather last year’s policy schedule, the new renewal schedule, any endorsements, and a record of changes to what you insure. For a car, that could mean a different driver or new annual mileage. For a home, it may mean a renovation, new work equipment, or more valuable items. The most useful comparison is between the old and new terms, not just two premiums.
Check what the policy actually protects
Read the summary of covered events. Then read the exclusions. An exclusion states what the insurer will not pay for under certain conditions. A policy may cover one kind of water damage but not another, or may protect ordinary household goods but place a lower limit on expensive devices. Names such as “comprehensive” do not mean every possible loss is included.
Ask three questions for each major risk: Is it covered? Up to what limit? What must happen for the claim to qualify? Write down unclear terms for the insurer. Get a written answer if the point matters to your decision. A clear email is easier to rely on than a vague memory of a sales call.
Look at any optional benefits included last year. Are they still active? Did a previous claim change terms? If the insurer has removed cover you use, the lowest quote may not be the best value. Do not assume an add-on follows you when you switch insurers.
Recalculate the deductible and claim limit
A deductible, also called an excess in some markets, is the amount you may pay toward a covered claim before the insurer pays its share. A higher deductible may lower the premium, but only makes sense if you can afford that share after an unexpected loss. A low monthly premium can be costly if it leaves you unable to claim for a moderate repair.
Imagine two hypothetical policies. Policy A costs 300 units per year with a 150-unit deductible. Policy B costs 240 with a 500-unit deductible. The cheaper policy saves 60 each year but puts 350 more at risk on a qualifying claim. These are example figures, not quotes. Your decision should reflect your cash reserve, the chance of a claim, and the policy’s limits.
Check whether limits apply per item, per incident, or for the full policy term. Some policies include sublimits for electronics, valuables, temporary accommodation, or specialist repairs. A total cover figure in a headline can hide smaller amounts for the things you care about.
Update the value of what you insure
Replacement costs can rise even if you have not bought anything new. Review the price to repair or replace property in your local market. Do not confuse the market sale price of a building with the cost to rebuild it. For a vehicle, ask which value method the insurer will apply after a total loss. For belongings, check whether the policy pays new replacement cost or a value reduced for age and use.
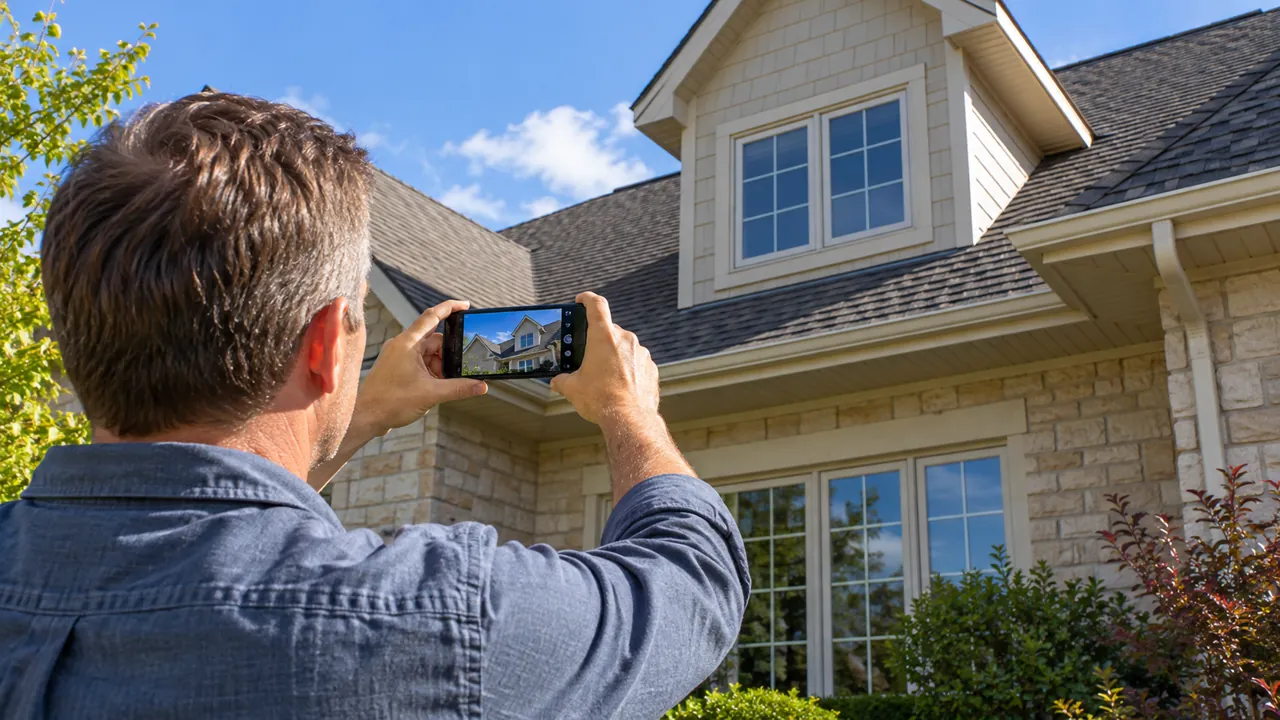
Take a few fresh photos of major items and keep receipts where you have them. A quick room-by-room inventory gives you a clearer view of what would need replacing. Keep copies in a safe place separate from the insured property. Update your inventory when you buy high-value items or change rooms.
What changed this year?
Think beyond price inflation. Did someone move into or out of the home? Did you begin working from home? Did you install solar panels, renovate a room, store items elsewhere, or take a longer trip? Each change may affect the insurer’s view of risk or the definition of an insured item. Tell the provider about material changes through its official channel.
Look closely at weather and disaster cover
Storm, flood, fire, and earthquake cover may have distinct terms. One event might be included while another needs a separate policy or endorsement. Read the definition of the event, the deductible, waiting periods, and any restrictions that apply near the renewal date. If you live in an area with changing risks, ask the insurer how those risks are treated.
Insurance is not a substitute for prevention. Taking reasonable steps to protect a property may reduce damage, though it does not guarantee a claim. Keep evidence of major maintenance such as roof work or safety upgrades. Ask whether the insurer requires specific maintenance or notification before the renewal.
Compare quotes on equal terms
When seeking another quote, copy the same coverage limits, deductibles, drivers or occupants, property details, and optional benefits. If one provider quotes less because it excludes something important, that is not a like-for-like saving. Compare how claims are reported and who handles repairs, not only the price.
Check the insurer’s licensing and complaint route using the appropriate local regulator. The National Association of Insurance Commissioners provides consumer resources in the United States, including questions to ask about cover. Readers elsewhere should use their own insurance regulator or recognized consumer body for local guidance.
Ask whether taxes, administration fees, installment charges, or cancellation fees change the true annual cost. Paying monthly can make a bill easier to manage, but it may cost more in total. Add up every scheduled payment and compare it with the annual option.
Before you renew, confirm the details
A useful renewal review ends with a specific decision. If you keep the policy, make sure the insurer has the right details and you can afford both the payment and the deductible. If you switch, confirm the replacement cover starts before the old one ends. Do not cancel existing cover while an application is still pending.
A ten-minute renewal checklist
- Check renewal and cancellation dates.
- Compare old and new premiums and fees.
- Read exclusions and changes in cover.
- Check each deductible and key limit.
- Update personal or property details.
- Review items that need special cover.
- Check disaster and weather conditions.
- Compare like-for-like quotes.
- Confirm the claims and complaint process.
- Save the final schedule in a secure place.
Common questions
Will the cheapest renewal always be best?
No. A cheaper quote may have a higher deductible, lower limits, fewer benefits, or a less suitable claims process. Compare what you would get after a realistic loss.
Should I renew even if I have made no claim?
A claim-free year does not mean your risks and cover stayed the same. Review the policy at every renewal. It is often the easiest time to correct details and compare alternatives.
Can I make changes after paying?
Sometimes, but terms and fees depend on the policy and local law. Ask the insurer what changes are allowed, when they take effect, and whether there is a fresh waiting period.
If the renewal concerns a vehicle, our auto insurance cost guide can help you weigh savings against needed protection.
Make renewal a decision, not a habit
A good renewal review does not need to be complicated. Start early, check the main risks, compare real costs, and document the answer. The aim is not to buy the most cover you can find. It is to understand the loss you are asking an insurer to share, what you would still pay yourself, and whether the policy fits your life today.
A quick test before you renew
Put last year’s policy next to the new one. Start with the price, but do not stop there. Look at the sum the firm will pay for a claim. Then read what it will not pay for. A cheap plan may leave you with a large bill.
Say your home now has a new bike and a work laptop. The old list may not show them. Ask if they need to be named on the plan. Take fresh photos and keep proof of what they cost. A clear list helps if you must make a claim.
Next, check your own share of each claim. This is the cash you pay first. A high share can cut the price of a plan, but you may need more cash if a loss takes place. Pick a share you could pay from your own funds.
Call the firm if a term is not clear. Ask them to show the answer in the policy text. Keep the answer with your files. Shop for a new quote in good time, so you can read it with care.

4 Comments