
Insurance Claim Denied? How to Review the Decision and Appeal
First steps: Read the letter that says your claim was denied. Find the reason it gives. Check your policy and save the proof you have. Ask the insurer how to seek a review. Keep the dates and case number. The rules vary by place, so check your local process.
An insurance claim denial can feel final. It may not be. The insurer may need more proof, may have read a clause in a way you do not agree with, or may have made a mistake. This guide shows how to check the letter, gather facts, and use the appeal or complaint path where you live. It does not promise that a claim will be paid.
Read the denial letter before you reply
Start with the exact reason given. The notice may say that the event is not covered, a time limit was missed, a document is missing, or the claim amount is above a cap. Those are different issues. The next step depends on the reason. Do not send a long angry email before you know what you need to answer.
Write the claim number, date of the decision, and the rule the firm cites. Note any date by which you must ask for a review. Rules vary by country and type of policy. Some health claims have special rights. Home, car, travel, and work claims may follow different paths.
The National Association of Insurance Commissioners lists unfair delays and claim denials among issues that can lead to a consumer complaint in the United States. Local regulators elsewhere may offer other routes. Look up the official body for your policy.
Match each reason to the policy
Open the policy you had on the day of the loss. Read the main cover section, any exclusions, the list of limits, and any terms for making a claim. The first page of an advert is not enough. The full contract and local law matter. If the insurer cites a clause, read the lines before and after it.
For example, a home claim may be denied as flood damage even though the owner thought heavy rain was covered. The key may be how the policy defines flood, surface water, or a storm. Ask the insurer to point to the exact wording. If the meaning is not clear, ask for a written note explaining how it applies to your loss.
Do not guess what a term means
Words such as excess, waiting period, pre-existing condition, and wear and tear have a role in a claim. The meaning may differ by policy. Ask what facts the insurer used, not just which label it chose. Keep your tone calm and specific. A short question with a clear document can be more useful than a broad complaint.
Build a clean claim file
Keep the denial letter, signed policy, claim form, photos, bills, repair quotes, medical records if relevant, and all messages from the firm. Put them in date order. Name each file so you can find it. Keep a copy in a safe place. Do not send unneeded private data to an unknown email address.
Write a one-page timeline. Include when the loss took place, when you found it, when you told the insurer, what proof you sent, and when the reply came. A clear timeline helps someone else see the case fast. It can also show where a delay or missing step may have occurred.
Do not change a bill, photo, or date to make the case stronger. If an item is wrong, mark the error and add a true note. A clean record builds trust. A false record can harm a valid claim and may break the law.
Ask for a review in plain terms
Follow the route set out in the denial letter. It may be an internal review, an appeal form, or a complaint to a claims team. State the claim number and which part of the decision you question. Say what result you seek and why. Add only the documents that bear on that point.
A useful appeal might say: The letter says no proof of purchase was sent. I attach the dated receipt and the bank record for the same item. Please review the claim with these files. That is clearer than a long note that repeats how upset you feel. You can still say the result has caused stress.
Ask for a reply date and a case number. If a claim involves urgent care or a risk to health, ask whether an urgent review exists. The NAIC health claim appeal guide notes that an expedited path may matter in serious cases in its jurisdiction. Do not assume the same time limits apply elsewhere.
Know when expert proof can help
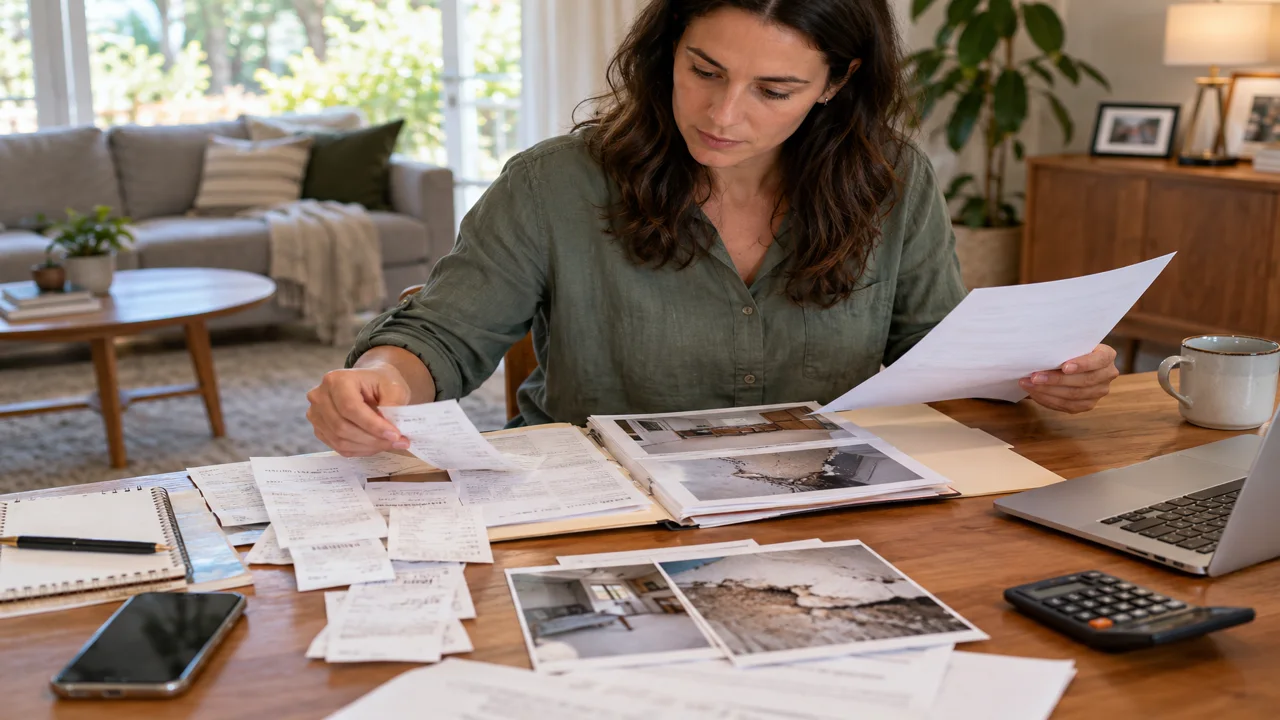
A mechanic, builder, doctor, or other skilled person may be able to explain the cause or extent of a loss. Choose someone with the right license where one is required. Ask for a short written report with facts, dates, photos, and a clear conclusion. A broad opinion without evidence may not change the result.
Think about cost before you order a new report. If a disputed claim is small, a costly expert note may not be worth it. Ask the insurer which missing facts it needs. You may already have enough proof in repair records or a medical file.
Keep contact records and deadlines
Write down each call, name, date, and key point. Follow up by email or the secure claim portal so there is a record. Put the next due date on a calendar. If you need more time to collect proof, ask in writing whether an extension is possible. Do not assume an extension exists until the firm confirms it.
Use the official claims number or portal. Scammers sometimes contact people after a loss and offer to recover money for a fee. Do not share a login code, full bank data, or copies of private files with an unknown helper. Check a professional’s license and fees before you hire them.
Use the right outside complaint route
If the internal review fails, check whether an insurance regulator, ombudsman, court, or other dispute service can hear the case. Each country has its own rules. Some services are free. Others need you to finish the insurer’s own complaint path first. Ask for the official steps and time limit.
A regulator may check whether the firm followed law and fair process, but it may not have power to order payment in every case. An ombudsman may handle certain kinds of claims only. Find out what the body can do before you send your full file. Keep a copy of everything submitted.
If you hire a lawyer or claims adviser, ask for the full fee and any conflict of interest. An adviser who promises a guaranteed payout is a warning sign. A sound review should explain both the strong and weak facts in your case.
What if the claim is only partly paid?
A small payout may reflect a claim cap, excess, age-based value, or the insurer’s repair estimate. Ask for the math. Compare it with the policy and your own proof. If a repair quote is higher, explain why and attach it. Do not argue only from the amount you hoped to get.
For example, a tool bought for 1,000 local units may be worth less under a plan that accounts for age and wear. Another plan may pay for the cost of a new item, up to a limit. The result depends on the contract. Ask which method the firm used and where it is written.
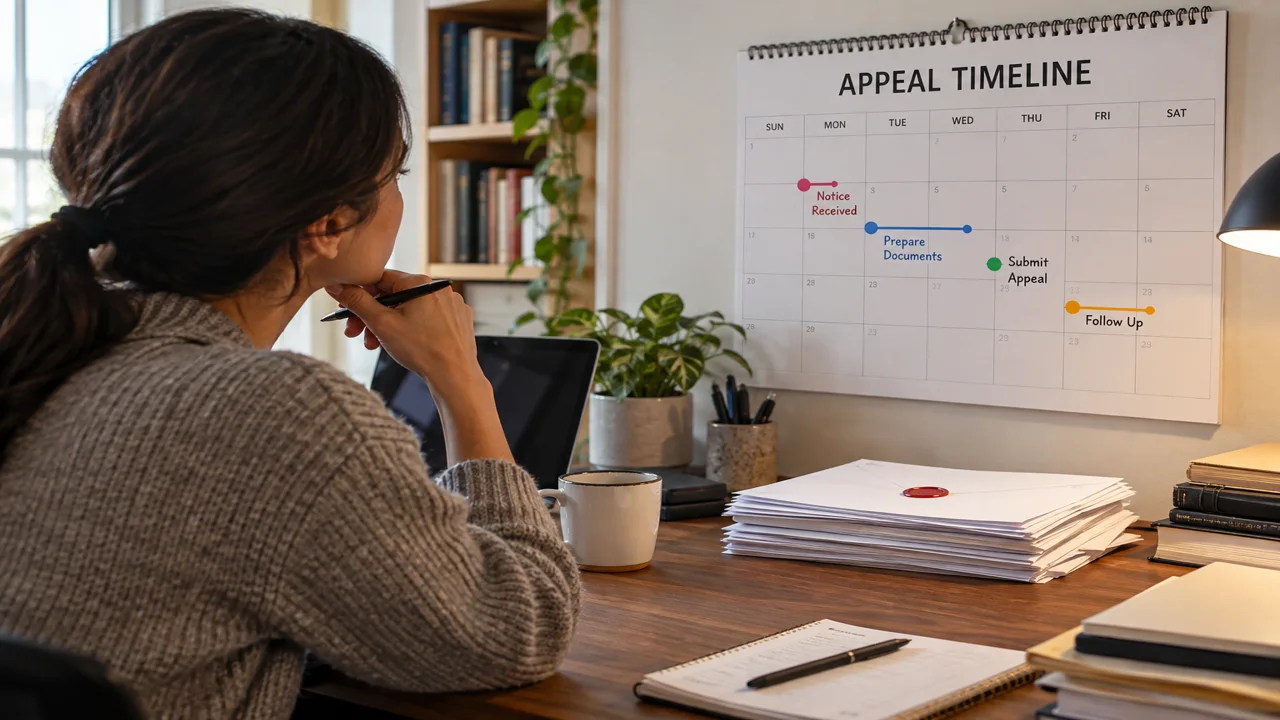
A short appeal checklist
- I know the exact reason for the decision.
- I have read the policy clause the firm cites.
- I have a dated file of proof and messages.
- My appeal answers the specific reason given.
- I know the next deadline and official contact route.
- I have checked the outside complaint options where I live.
For a real example of coverage terms to check before a loss, see our auto insurance coverage guide. Claims rules depend on the specific policy.
The bottom line
A denial is a reason to check the facts, not a reason to give up or assume the insurer is wrong. Read the letter, compare it with the policy, and send focused proof through the proper route. Keep dates and copies. If the answer still seems wrong, use the local complaint process or seek licensed advice. Good records help you make the strongest fair case.

2 Comments