HSA-Eligible Health Plans in 2026: How to Compare Premiums, Deductibles, and Total Cost
A health plan with a lower monthly premium can still become expensive if you need frequent care. A plan with a higher premium can also be poor value if you rarely use medical services. That is why health insurance should be compared by total annual cost, not by premium alone.
HSA-eligible health plans add another factor: a Health Savings Account. An HSA can help you pay qualified medical expenses with tax advantages, and unused money can stay in the account for future years.
This guide explains the 2026 HSA rules, how HSA-eligible plans work, and how to compare two plans using realistic scenarios. It is designed for people choosing employer coverage or Marketplace coverage and trying to make a practical decision.
For 2026, the Internal Revenue Service sets the HSA contribution limit at $4,400 for self-only coverage and $8,750 for family coverage. A qualifying high deductible health plan generally must have a deductible of at least $1,700 for self-only coverage or $3,400 for family coverage, with maximum in-network out-of-pocket expenses of $8,500 and $17,000 respectively under the HSA rules.
What makes a health plan HSA-eligible?
An HSA is not available with every high-deductible plan. The plan must meet federal HSA eligibility rules, and you must also meet individual eligibility requirements.
For 2026, a qualifying high deductible health plan, or HDHP, must meet the deductible and out-of-pocket limits set by federal law. The HealthCare.gov HSA guide lets Marketplace users filter for plans that work with an HSA.
2026 HSA numbers
| Rule | Self-only | Family |
|---|---|---|
| HSA annual contribution limit | $4,400 | $8,750 |
| Minimum HDHP deductible | $1,700 | $3,400 |
| Maximum annual out-of-pocket under HSA rules | $8,500 | $17,000 |
These are federal HSA rules. Your actual plan can have different cost-sharing details as long as it qualifies.
What is an HSA?
A Health Savings Account is a tax-advantaged account you can use for qualified medical expenses. The money belongs to you, not your employer.
HSA funds can generally roll over from year to year. You do not have to spend the balance by December 31. That is a major difference from many flexible spending accounts.
The three common HSA tax advantages
- Eligible contributions may reduce taxable income or may be made pre-tax through payroll.
- Investment growth inside the account can be tax-deferred.
- Withdrawals for qualified medical expenses can be tax-free under federal rules.
State tax treatment can differ, so check your state’s rules.
Do not compare plans by monthly premium alone
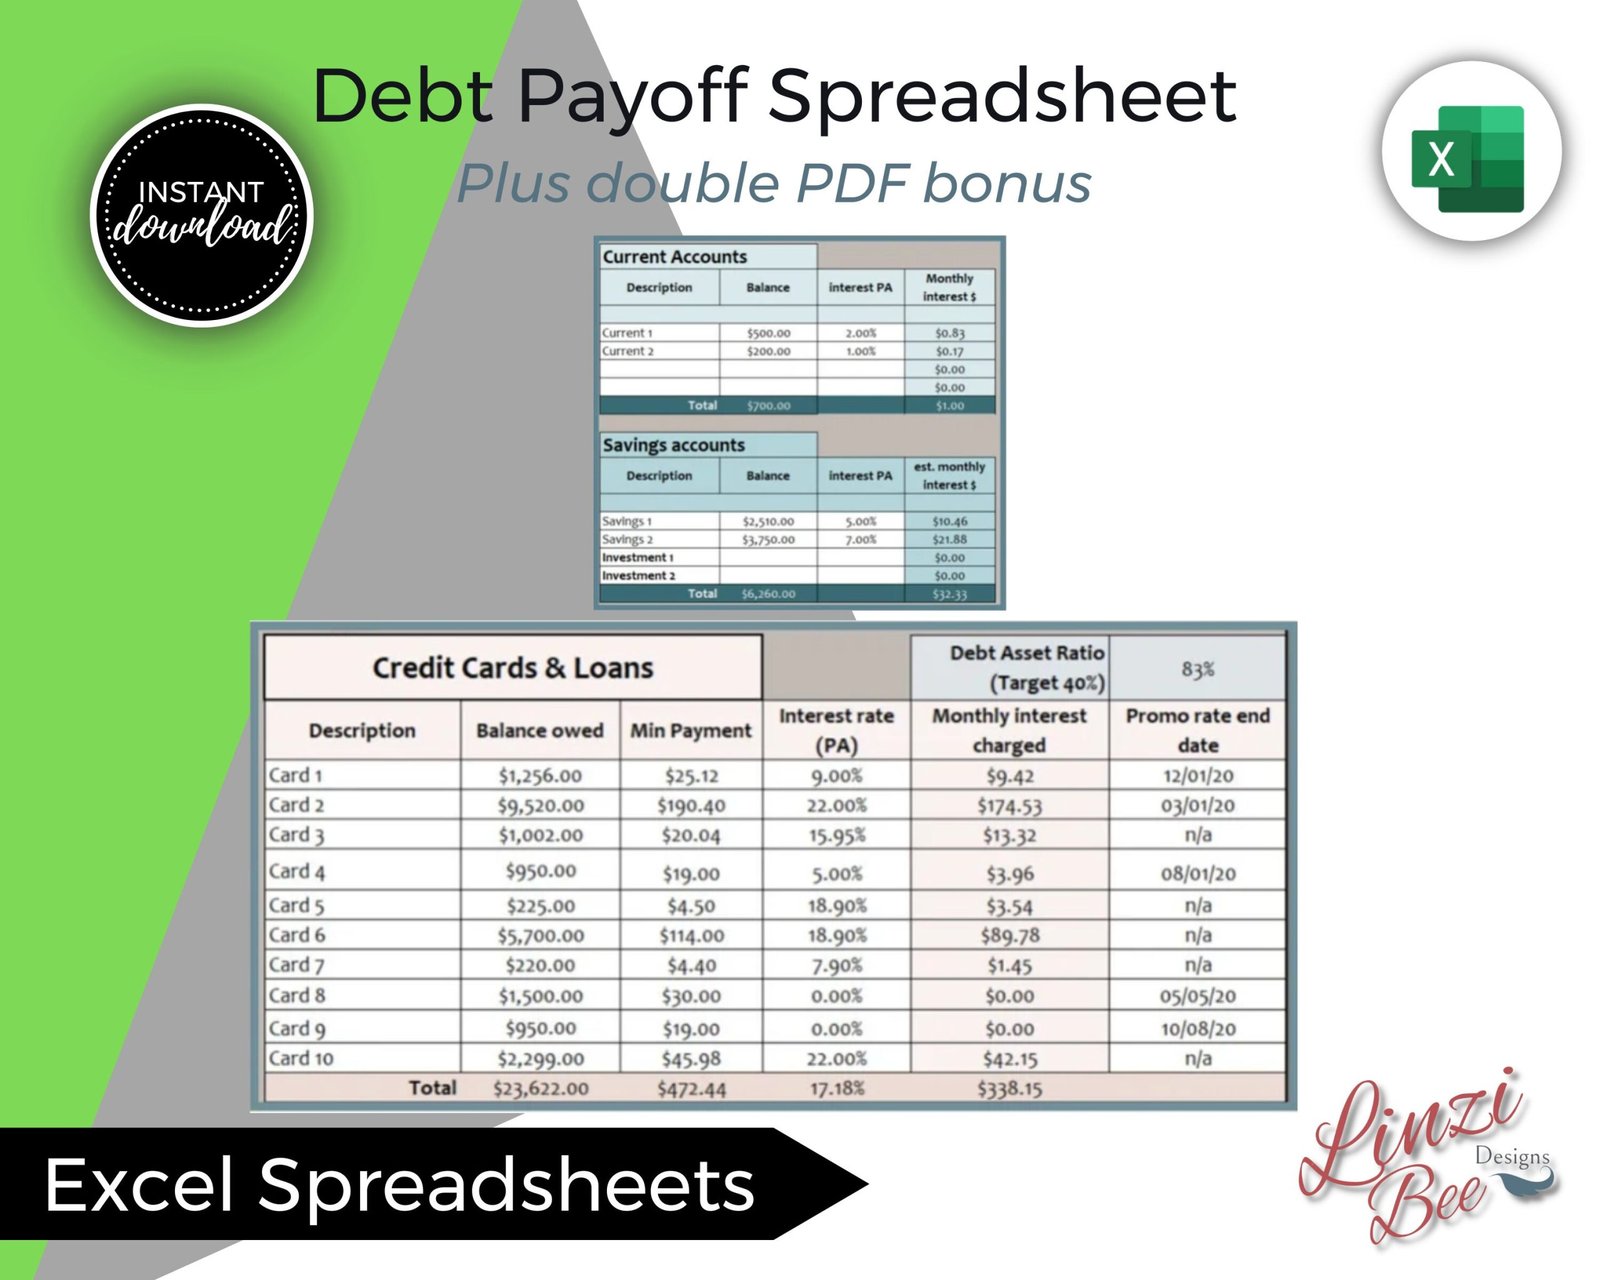
Start with the annual premium. Multiply your monthly employee or household premium by 12. Then add likely out-of-pocket costs.
A simple annual-cost formula is:
Annual premiums + expected medical spending – employer HSA contribution = estimated annual cost
For a worst-case comparison, replace expected medical spending with the plan’s out-of-pocket maximum, while remembering that premiums are usually separate from the out-of-pocket limit.
Step 1: calculate annual premiums
Suppose Plan A costs $180 per month and Plan B costs $340 per month.
- Plan A annual premium: $2,160
- Plan B annual premium: $4,080
Plan A starts $1,920 cheaper before any medical care. But that does not automatically make it the better plan.
Step 2: compare deductibles
The deductible is the amount you may have to pay for covered services before the plan starts sharing certain costs, subject to the plan rules.
An HSA-eligible plan usually has a higher deductible. That can be manageable if you have enough savings, but stressful if a large bill early in the year would force you to use credit.
Ask this question
If you had a $2,500 medical bill in February, could you pay your share without carrying credit card debt?
If the answer is no, a low-premium HDHP may create more financial risk than the premium suggests.
Step 3: compare the out-of-pocket maximum
The out-of-pocket maximum is the most you generally pay in a year for covered in-network cost-sharing such as deductibles, copayments, and coinsurance. It does not usually include premiums, and out-of-network spending may follow different rules.
This number matters for people who want to understand the financial effect of a bad health year.
Worst-case example
Plan A costs $2,160 in annual premiums and has an $8,000 out-of-pocket maximum. Its rough worst-case in-network annual cost could be $10,160 before considering employer HSA contributions.
Plan B costs $4,080 in premiums and has a $5,000 out-of-pocket maximum. Its rough worst-case cost could be $9,080.
In a high-use year, the more expensive monthly plan may actually expose you to a lower total cost.
Step 4: include employer HSA contributions
Many employers contribute money to employee HSAs. Treat that contribution as part of the plan value.
If Plan A comes with a $1,000 employer HSA contribution, its effective cost improves by $1,000 compared with an otherwise identical plan without that contribution.
Check when the employer deposits the money. Some employers fund the full amount in January. Others contribute each pay period.
Step 5: compare coinsurance and copays
After the deductible, a plan may require coinsurance. For example, you might pay 20% of an allowed charge while the insurer pays 80% until the out-of-pocket maximum is reached.
Another plan may use copays for office visits or prescriptions.
Do not compare only the deductible. Look at how costs work after the deductible too.
Step 6: check the prescription drug rules
If you take regular medications, review the drug formulary before enrolling. Check whether each drug is covered, its tier, whether the deductible applies first, mail-order options, prior authorization rules, and specialty pharmacy requirements.
A cheap plan can become expensive if an important prescription is poorly covered.
Step 7: check the provider network
A plan is not useful if your preferred doctor, hospital, therapist, or specialist is out of network and you do not want to switch.
Use the insurer’s current provider directory, then call the provider office to confirm. Network listings can be outdated.
If you are planning surgery, pregnancy care, ongoing therapy, or specialist treatment, verify each major provider and facility.
HSA vs FSA: do not confuse them
An HSA and a health flexible spending arrangement are different.
HSA money belongs to you and generally rolls over. An FSA is usually tied to an employer plan and may have use-it-or-lose-it rules with certain allowed carryovers or grace periods.
For 2026, the federal health FSA salary-reduction limit is $3,400, according to the IRS 2026 tax adjustment guidance.
Having a general-purpose health FSA can affect HSA eligibility. A limited-purpose FSA for dental and vision expenses may be compatible in some situations. Check the plan terms.
Who may like an HSA-eligible plan?
People with low expected medical use
If you rarely use care beyond preventive services, lower premiums plus HSA contributions can be attractive.
People who can handle a high deductible
An HSA plan works better when you have cash reserves to pay medical bills before the plan starts sharing more of the cost.
People who want a long-term medical savings account
Unused HSA money can accumulate. Some HSA providers allow investing once the cash balance reaches a certain level.
Who may prefer a lower-deductible plan?
A lower-deductible or richer plan may be worth the higher premium if you expect frequent specialist visits, expensive prescriptions, therapy, planned procedures, pregnancy care, or other high use.
It can also be useful if cash flow matters more than long-term tax savings. Paying predictable premiums may be easier than facing a large deductible early in the year.
Real-world example: low medical use
Chris is single, healthy, and uses only routine preventive care most years. The employer offers:
- HSA Plan: $150 monthly premium, $2,000 deductible, $6,500 out-of-pocket maximum, $800 employer HSA contribution.
- PPO Plan: $310 monthly premium, $750 deductible, $4,000 out-of-pocket maximum, no HSA contribution.
The HSA plan costs $1,800 in annual premiums. The PPO costs $3,720. Before medical spending, the HSA plan is $1,920 cheaper, and the employer adds $800 to Chris’s HSA.
If Chris has a low-use year, the HSA plan may offer strong value. But Chris still keeps enough cash to handle the deductible.
Real-world example: high medical use
Maria expects regular specialist care and expensive medication. She compares the same two plans.
The HSA plan’s lower premium still helps, but Maria estimates she may spend near the out-of-pocket maximum. She compares the total possible annual cost rather than focusing on the monthly premium.
If the PPO has better drug coverage, a lower maximum, and a stronger specialist network, paying more each month may reduce total risk.
Plan for the first 90 days, not only the full year
Annual cost is important, but cash flow can decide whether a plan feels manageable. A high-deductible plan can be inexpensive over 12 months yet difficult in January or February if a large medical bill arrives before your HSA balance has grown.
Check when employer HSA money arrives
If an employer promises $1,200 for the year, find out whether the full amount appears on January 1 or arrives as $100 each month. That timing changes how much cash you need at the start of the year.
Build a medical cash buffer before enrollment starts
If you choose a $3,000 deductible plan, you do not necessarily need $3,000 in cash on day one, but you should know how you would handle an early bill. A separate savings buffer can keep a deductible from turning into high-interest credit card debt.
Ask how bills are processed before paying them
For non-emergency care, wait for the insurer’s explanation of benefits when appropriate. It shows the allowed amount, what the plan paid, and what you may owe. Compare it with the provider bill. If the numbers do not match, call the insurer or provider before paying the full amount.
Also ask providers about payment plans for large balances. A no-interest provider plan may be easier on cash flow than draining an emergency fund at once. The best health plan is not only the one with the lowest theoretical annual cost; it is the one your household can finance safely when care happens.
Should you invest HSA money?
An HSA can be used as a spending account, a long-term savings account, or both.
If you expect to use the money for medical bills this year, keep enough in cash. Investing money you may need next month can create market risk.
If you have a large balance beyond near-term medical needs, you may consider long-term investments offered by the HSA provider. Compare fees and investment choices.
Save medical receipts
Many HSA owners keep records of qualified medical expenses. Good documentation can help if you reimburse yourself later or need to support the tax treatment of a withdrawal.
Save itemized receipts, explanation-of-benefits statements, and proof of payment. A simple digital folder organized by year is often enough.
Common HSA mistakes
Contributing when you are not eligible
Eligibility can change if you gain other disqualifying health coverage. Check the rules rather than assuming your plan name is enough.
Ignoring employer contributions when calculating your limit
Employer HSA contributions generally count toward the annual contribution limit. Track the combined total.
Spending HSA money on nonqualified expenses
Nonqualified withdrawals can create taxes and penalties depending on your age and circumstances.
Choosing an HSA plan only for the tax deduction
Insurance comes first. A poor provider network or unaffordable deductible can outweigh the tax benefit.
Investing every dollar
Keep enough cash for likely near-term medical spending.
A practical health-plan comparison worksheet
For each plan, write down monthly premium, annual premium, deductible, out-of-pocket maximum, primary care cost, specialist cost, emergency room cost, coinsurance, prescription costs, employer HSA contribution, important doctors in network, and important drugs covered.
Then calculate three scenarios: low use, expected use, and high use. This gives you a much better decision than comparing premiums alone.
Quick answers
What is the HSA contribution limit for 2026?
$4,400 for self-only coverage and $8,750 for family coverage, subject to eligibility and other contribution rules.
Does HSA money expire?
No. Unused HSA money generally rolls over from year to year.
Can I use HSA money for insurance premiums?
Usually not, though there are specific exceptions under federal tax rules. Check current IRS guidance.
Is every Bronze plan HSA eligible?
Marketplace rules have changed over time. Use the current HealthCare.gov HSA filter and plan documents rather than relying only on metal level.
Can I keep my HSA if I change jobs?
Yes. The HSA belongs to you. Future contribution eligibility depends on your health coverage.
Conclusion: compare total annual cost and cash-flow risk
An HSA-eligible plan can be a powerful option, but the tax benefits should not distract you from the insurance math.
Start with annual premiums. Add likely medical spending. Compare the deductible and out-of-pocket maximum. Subtract employer HSA contributions. Check prescriptions and provider networks. Then ask whether you could afford a large bill early in the year.
For 2026, the HSA contribution limits are higher than in 2025, which gives eligible savers more room. But the best plan is still the one that balances coverage, total cost, cash flow, and risk for your household.
This article is for general educational purposes. Health plan rules, HSA eligibility, tax treatment, and coverage vary. Review official plan documents and consider qualified tax or benefits advice for personal decisions.